Home
You’re currently viewing our content for All Regions.
You can switch to a different region:
November 9, 2026
Every couple of years – aligned to inevitable industry cycles – the technology ecosystem is told to reinvent itself.
Remember, cloud was going to cut partners out of the deal, marketplaces were going to make the channel redundant and now AI is cast as the great disruptor.
Because keynotes today have a familiar ring to them; the old partner model is broken, and only those bold enough to tear it up will survive.
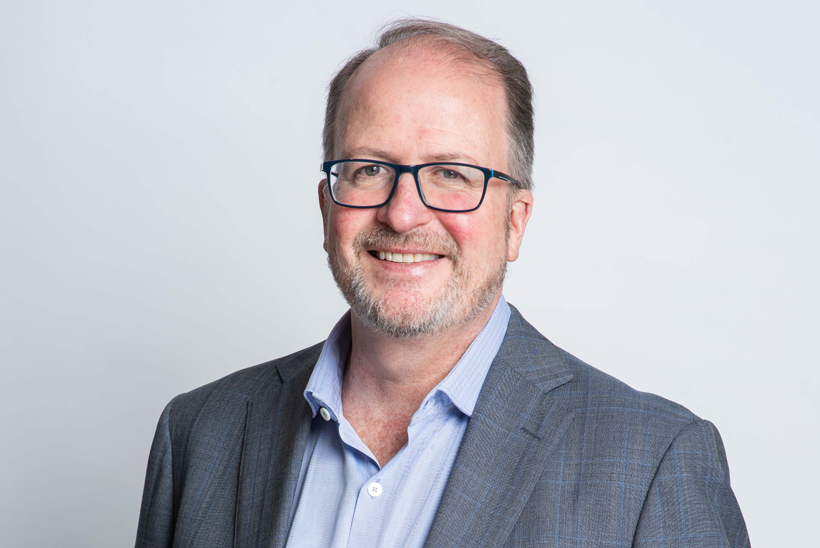
Tim Sullivan isn’t buying it.
“No, the model does not require reinvention – it requires disciplined evolution,” stated Sullivan, speaking as CEO and Co-Founder of Coevolve. “The core purpose of partners remains unchanged: extend vendor reach, provide expertise and deliver outcomes at scale.”
Perhaps an unfashionable position to take in a market obsessed with revolutions. But Sullivan holds it without apology.
“The fundamentals have not changed,” he added.
“Focus, discipline and delivering measurable client outcomes remain the core of a successful partner business. Demand is steady, but expectations are sharper. Clients want clarity, speed and demonstrable value aligned to business outcomes – not just technology deployment.”
The numbers support this assessment.
According to Moxie Metrics – Partner Ecosystem: Australia FY26 – 76% of Australian partners grew revenue year-on-year. But growth was moderate rather than spectacular because only 12% grew by more than 20%, while the largest group (36%) grew by between 1% and 10%.
Steady, yes. Effortless, no.
That doesn’t mean the market is easy, however. The pressure is real but it isn’t coming from where most partners would look for it.
The obvious suspect is the customer – the tighter budget, the extra sign-off, the project pushed into next year.
Sullivan points the other way, however. Up the supply chain, to the vendors that partners sell on behalf of.
High-growth and emerging technology companies are under constant pressure from investors and boards to show momentum, and that pressure has a habit of rolling downhill.
A vendor that needs to land its quarter pushes for deals, and a partner that goes along with it can end up selling what the vendor needs sold this quarter rather than what the client needs for the next five years.
“The biggest shift is upstream,” Sullivan explained.
“There’s increased pressure on vendors, particularly high-growth and emerging players needing to prove traction. This can drive short-term, transactional sales behaviours that are sometimes misaligned with long-term client value.”
The cost of that pressure already shows up in partner financials.
Supplier or vendor price increases pushed up operating costs for 59% of Australian partners in FY26, second only to salaries (65%), according to Moxie Metrics. Rising supplier costs weighed on profitability for 53%.
Pressure from upstream lands on price as well as on behaviour, and partners are left to decide whether to absorb the increase or pass it on.
At the other end of the deal, the clients are in no hurry. Coevolve works with large global enterprises, and those buyers have become more careful, not less.
“Deal cycles remain deliberate rather than compressed,” Sullivan explained. “What has changed is scrutiny: more stakeholders, higher standards and stronger validation requirements.”
Put those two forces together and the partner sits squarely between them – a vendor on one side that wants the deal closed now, and an enterprise on the other that wants every assumption tested before it signs anything.
Side with the vendor’s clock and you may win the quarter at the cost of the client’s long-term trust.
“Our response remains the same: we play the long game,” Sullivan outlined.
“We prioritise client interests and long-term relationships. We take a pragmatic, multi-vendor approach aligned to client requirements, and avoid short-termism that erodes client trust.”
Playing the long game means accepting that not every conversation has to end in a sale. A client still working out what it needs doesn’t require a deployment pitch, and a client two years into running a service doesn’t need to be sold the same thing again.
But what it may need is a trusted voice to advise that the market has moved, and that the service should move too.
“We have always been respectful of where the client actually is in their lifecycle,” Sullivan said.
“We add value of different types, as appropriate: at the assess phase, when they are ready for deployment, in ongoing management for BAU, or at the optimisation stage as their needs and the market change. That is specifically reflected in our company name, Coevolve.”
The name sums up the whole philosophy of the Sydney-based business, which launched to market in 2014.
Reflective of the name, the partner doesn’t arrive, deliver and leave. Instead, the business evolves alongside the client – assessing, deploying, running and then reshaping the service as the business and technology requirements change in parallel.
The relationship is the product, and the technology is what gets swapped out over time. It is also where the money in the channel is heading.
According to Moxie Metrics, managed services contributed to the revenue of 86% of Australian partners in FY26, against 55% for one-off product sales. The partners in the strongest position treat the first project as the opening of a relationship, not the whole of it.
The macroeconomic picture also adds its own complications, and Sullivan doesn’t play them down.
For a business delivering services to enterprises across dozens of markets, the problems are rarely global in any tidy sense. They show up as a lead time in one country, a constrained part in another and a vendor struggling in a third.
“Macroeconomic conditions are creating friction,” he acknowledged.
“There is supply chain variability – chip and memory constraints, for example – which continues to impact delivery timelines. Global delivery is more fragmented, with uneven conditions across regions and vendors.”
Friction is not the same as a freeze, though. Investment hasn’t dried up but it is being spent more carefully, on fewer and better-justified priorities.
“Budget scrutiny is higher, but investment has not stopped,” Sullivan expanded.
“Clients are prioritising initiatives that drive business resilience, cost efficiency and long-term scalability through digital and AI-led initiatives.”
Buyers closer to home tell a similar story.
According to Moxie Metrics – Mid-Market Outlook: Australia FY27 – 76% of Australian mid-market organisations expect their technology spending to rise over the next year, and only 3% expect a cut.
But when they weigh up a major initiative, long-term scalability (39%), cost predictability (36%) and clear business outcomes (33%) all count for more than speed to value (23%).
The budget is there, and it goes to whoever makes the most durable case for it.
“We build flexibility into delivery models and sourcing strategies,” Sullivan added.
“We always iterate and strengthen our multi-vendor and telco-independent approaches to mitigate supply risk. And we focus commercial conversations on total cost of ownership and business outcomes, not just upfront cost.”
Much of the ecosystem’s current hand-wringing comes down to a single question: are partners suppliers or advisers?
Sullivan rejects the idea that one has to replace the other because both models are alive and well, and both have a job to do.
“The market continues to support both transactional and strategic partner models,” he explained.
“Transactional partners – distributors and marketplaces, for example – optimise for scale, efficiency and fulfilment. Strategic partners focus on long-term value creation and complex problem-solving.”
Where partners come unstuck, however, isn’t by picking the wrong model.
Rather by refusing to pick one at all – adding a resale line here, a new practice there and a marketplace listing somewhere else, until nobody, the partner included, can say what the business actually stands for.
“The key is clarity of your role and staying true to who you are,” Sullivan advised.
“Partners must optimise for the value they are designed to deliver, rather than attempting to be everything to all people or being overly opportunistic.”
For partners that have chosen the strategic path, set the bar high. There are three capabilities that Sullivan calls ‘non-negotiable’, and the first is deliberately pointed at the certification badges that fill so many partner websites.
“Deep technical expertise across the life cycle – not just vendor certifications, but real-world, diverse implementation and optimisation experience,” he highlighted.
“Strong client intimacy – understanding business context, not just technical requirements, with a long-term relationship mindset. And the ability to bridge objectives, aligning technology decisions with commercial and operational outcomes.”
Each one on its own is common enough. Plenty of partners have strong engineers, and plenty have good account managers.
The value, Sullivan argued, comes from having all in play at once.
“This combination is what makes a partner genuinely valuable as both a technical expert and a trusted advisor,” Sullivan noted. “We aim to deliver the best of both worlds: long-term business understanding, and the underlying flexibility to evolve the solutions underneath the end-to-end service.”
Few partners have earned that status.
For example, only 10% of Australian mid-market organisations regard their external MSP as a critical strategic adviser, according to Moxie Metrics.
In the mid-market, the rest describe the relationship as tactical and project-based (35%), operational (34%) or transactional (21%).
Ask those same organisations what matters most in a partner, and the list reads a lot like Sullivan’s: technical expertise (42%), understanding of the business (37%) and trusted advice (35%), all ahead of cost competitiveness (30%).
According to Sullivan, partners pulling ahead of the pack share three critical attributes.
The first starts with the client’s problem rather than the vendor’s price list.
“There must be a deep understanding of client pain points, business priorities and commercial constraints,” Sullivan advised. “That needs to translate into an ability to map vendor capabilities directly to measurable business outcomes.
“The second is true mastery of the technology domains and vendor ecosystem, and clear, unbiased articulation of strengths and weaknesses across competing solutions.”
The third is the least glamorous but arguably matters most.
Expertise and advice count for little if delivery falls over, and delivery credibility can’t be claimed – it has to be earned, site by site and reference by reference.
“Consistent execution requires strong delivery frameworks, automation and continuous improvement,” Sullivan said. “It’s a hard-won reputation, validated by client outcomes and references – we have sites under management in 82 countries, and growing.”
The Moxie Metrics data suggests that is where margin is now won.
Only 10% of Australian partners credited better pricing or margins for their profitability in FY26, while 37% pointed to efficiency and productivity gains. With less room to lift prices, the partners pulling ahead are the ones that deliver the work better, not the ones that blindly charge more for it without additional value.
Underneath all three, Sullivan puts people.
Frameworks and automation can be bought or built. The curiosity that keeps a team learning, and that pushes it to try new technologies before clients start asking, is harder to manufacture.
“Underpinning all three is, of course, the team,” Sullivan shared.
“We are fortunate to have high-calibre specialists who combine technical depth with curiosity and client focus. We work hard on a culture that values learning, adapts early to new technologies, and continuously improves how services are delivered.”
Which brings it back to evolution.
If the partner model doesn’t need tearing up, what does a leading partner actually look like? Sullivan reaches for an image that says a lot about how he sees the job.
“What defines a leading partner today is genuine, demonstrable expertise in their vendor portfolio across the full life cycle,” he continued. “It’s the ability to guide clients like a ‘sherpa’, ensuring the right solution is selected and successfully adopted over time.”
A sherpa knows the mountain better than anyone else on the expedition, carries much of the load and reads the conditions before the climbers do. But it is still the climbers who stand on the summit.
In an industry that hands out partner-of-the-year trophies and fills keynote slides with vendor logos, Sullivan is happy to stay out of the photo.
“They’re the heroes; we operate in the background as an enabler,” he added.
Guiding clients up the mountain only works if the guide has no reason to take them up the wrong route, however.
That is why independence comes up again and again in Sullivan’s answers. It isn’t a marketing line for him. It is the condition for the advice being worth anything.
“This requires independence of thought,” he added.
“We pride ourselves on our understanding of the broader market, the competitor landscape, and where each solution truly fits. In practice, this means moving beyond product alignment to outcome alignment.”
There is an apparent paradox in that.
A partner willing to steer a client away from a vendor might be expected to lose that vendor’s favour but Sullivan sees it the other way round. Vendors value a partner whose recommendations clients believe, and clients only believe recommendations that aren’t guaranteed in advance.
“Vendor partners also know us as a ‘safe pair of hands’ that clients trust to make the right call, even when it is not the easiest one,” Sullivan concluded.
Inform your opinion with executive guidance, in-depth analysis and business commentary.